Six years after the UK formally left the EU single market, the cumulative friction on trade, investment and regulatory compliance continues to reshape how British firms operate. The Trade and Cooperation Agreement removed the threat of tariffs on most goods, but it did not replicate the seamless access businesses had before. Customs declarations, rules of origin paperwork and the loss of free movement have all added layers of cost that compound over time.
The end of automatic mutual recognition for services created further drag. These costs arrived not as a single shock but as a steady, structural increase in the price of doing business across the Channel.
Read also: Impact of new tax laws on SMEs in the UK
Carbon border costs arriving in 2027 demand preparation now
One regulatory shift that has received less attention than tariffs or labour shortages is the UK Carbon Border Adjustment Mechanism (CBAM), scheduled to begin on 1 January 2027. Importers of covered goods, including iron and steel, aluminium, cement, fertiliser and hydrogen, will need to account for the carbon embodied in those imports.
For affected firms, 2026 is not a waiting period. It is the window in which they must secure emissions data from overseas suppliers, because HMRC guidance states that overseas producers must monitor and have their emissions independently verified for importers to report actual values. Where that verification is missing, importers will fall back on HMRC default values, which may be higher than actual emissions, raising the effective cost.
Related reading: Impact of the 2026 budget on the UK's business community
CBAM rates are designed to change quarterly, reflecting the effective UK carbon price and varying by sector and import quarter. Businesses importing covered products therefore need internal processes for checking the applicable rate and classifying goods by commodity code, not just a one-off calculation at the start of the year.
This is a new compliance obligation that did not exist under EU membership. It sits on top of customs declarations firms already manage, and it specifically affects supply chains in heavy industry and construction materials, sectors already dealing with post-Brexit border friction.
Trade friction and the gradual drag on UK productivity
The broad economic picture, as described by UK in a Changing Europe analysis, is that Brexit has made the UK economy smaller than it otherwise would have been. The mechanism is not a dramatic collapse but a gradual and cumulative drag on trade, investment and productivity.
Firms now face customs checks, rules of origin requirements and regulatory paperwork that did not apply when the UK was inside the customs union. Services businesses in regulated sectors lost market access rights that have not been replaced by equivalent arrangements. These are structural changes, not transitional bumps that fade with time.
The Office for Budget Responsibility continues to model the long-run effect of Brexit on trade intensity. Its analysis treats the departure from the single market and customs union as a persistent reduction in UK openness, feeding through to lower productivity growth. For individual businesses, that translates into narrower margins on cross-border sales and higher administrative costs per transaction.
Where the data gaps sit
Isolating the Brexit effect from other forces, notably the pandemic and the energy price surge of 2022-23, remains difficult. The OBR’s modelling relies on assumptions about the counterfactual (what would have happened had the UK remained), and those assumptions carry uncertainty. What the available evidence does show is a measurable shortfall in goods trade relative to pre-referendum trends, even after adjusting for global disruptions.
On the services side, comprehensive data is thinner. Bilateral services trade statistics lag goods data, and some regulatory divergence effects may take years to appear in official figures.
Business uncertainty in mid-2026: ONS survey evidence
The ONS Business Insights and Conditions Survey provides a real-time snapshot of how firms describe their operating environment. The survey consistently highlights economic uncertainty as a leading challenge affecting turnover for trading businesses, alongside labour costs for larger employers.
The survey also captures pricing pressures. Input cost increases remain widely reported, and a significant share of firms continue to expect the prices they charge to rise in the near term. These figures describe a business environment where cost pressures are persistent rather than easing. Labour costs, energy prices and input inflation overlap with the structural costs Brexit introduced, making it harder for firms to separate one source of pressure from another.
Regulatory divergence and the food sector consultation
A September 2026 government consultation proposed that Great Britain align with relevant EU authorisations for certain regulated food products. This is a specific, narrow proposal, but it illustrates a broader tension: where the UK diverges from EU rules, businesses selling into both markets face dual compliance costs; where it re-aligns, the sovereignty argument for Brexit weakens.
For food manufacturers and importers, the practical question is whether product formulations approved in the EU will be automatically recognised in Great Britain, or whether separate UK authorisation processes will continue. Each additional regulatory step adds time and cost before a product reaches shelves.
This kind of sector-by-sector regulatory negotiation is likely to recur across industries. The pattern, diverge and then selectively re-converge, creates ongoing uncertainty for businesses that need stable rules to plan investment.
Supply chain compliance is now a permanent cost layer
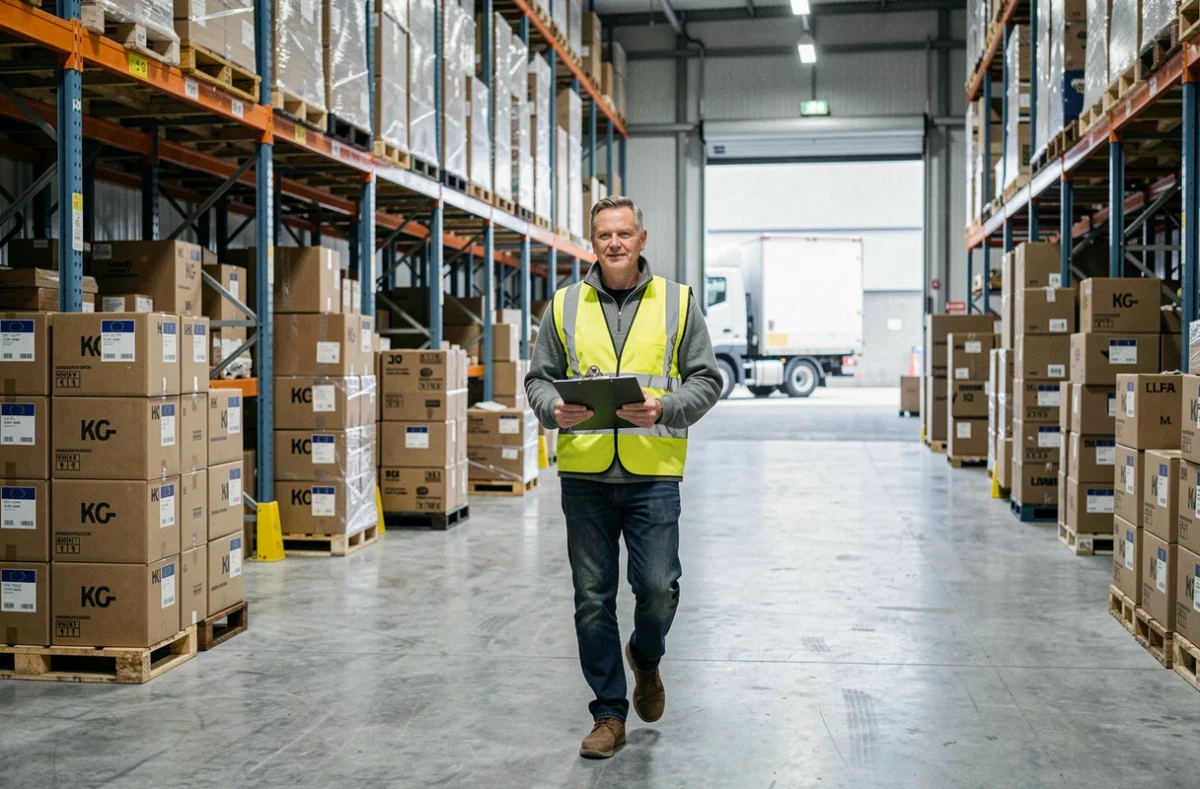
Before the referendum, a UK manufacturer sourcing steel from Germany or components from France faced no customs paperwork and no border checks. That has changed structurally. Every import now requires a customs declaration, and for goods covered by rules of origin provisions, firms must document where components were made to qualify for tariff-free treatment.
The CBAM adds another dimension. Importers of covered materials must now think about emissions data as a supply chain compliance requirement, not just a cost-of-goods question. Obtaining verified emissions figures from overseas producers is a new administrative burden, and the quarterly rate changes mean the cost is not predictable far in advance.
For smaller firms without dedicated trade compliance teams, these layers of paperwork represent a proportionally larger burden. Some have reduced cross-border activity rather than absorb the cost, which contributes to the trade intensity decline the OBR models.
- Customs declarations on every EU goods import, where none existed before 2021.
- Rules of origin documentation to maintain tariff-free status under the Trade and Cooperation Agreement.
- From 2027, carbon emissions reporting for imports of steel, aluminium, cement, fertiliser and hydrogen.
- Potential dual regulatory compliance for firms selling into both UK and EU markets.
The aggregate effect is that cross-border trade with the EU now carries a permanent administrative premium. Businesses that built their models around frictionless access have had to restructure, absorb costs, or in some cases withdraw from certain markets. Six years on, these are not teething problems. They are the new operating environment, and the regulatory calendar for 2027 suggests the compliance load will grow rather than shrink.