How far has the UK automotive industry actually moved toward electric vehicles by late 2026? The answer sits in a handful of telling figures: the two millionth battery electric car was registered earlier this year, yet the overall zero-emission vehicle (ZEV) share for the year has been revised downward. Measuring what accelerates and what drags on this transition reveals a market that is growing in absolute terms while underperforming against its own regulatory benchmarks.
UK electric vehicle registrations and market share in 2026
The Society of Motor Manufacturers and Traders (SMMT) upgraded its 2026 outlook to 2.093 million total new car registrations, reflecting a market that bounced back sharply from the disruption caused by 2025 tax changes. April 2026 alone saw a 24.0% year-on-year rise, reaching 149,247 units, the best April result since 2019.
See also: Legal reforms affecting UK property market in 2026
Battery electric vehicles held a 26.2% market share in April 2026, a robust figure for what is traditionally a low-volume month. The milestone of two million cumulative BEV registrations arrived in the same period.
The broader picture is less straightforward. SMMT revised the projected full-year ZEV share down to 26.8%, following weaker-than-expected demand in the first quarter. That gap between a rising total market and a softening EV share is the central tension of the UK’s 2026 transition story.
Recommended read: Brexit aftermath: economic implications for UK businesses in 2026
| Metric | Figure | Source |
|---|---|---|
| Total 2026 new car registrations (forecast) | 2.093 million | SMMT |
| April 2026 registrations | 149,247 units (+24.0% YoY) | SMMT |
| April 2026 BEV market share | 26.2% | SMMT |
| Full-year 2026 ZEV share (revised forecast) | 26.8% | SMMT |
| Cumulative BEV registrations (milestone) | 2 million | SMMT |
Battery supply chain gaps and the 2027 rules-of-origin deadline
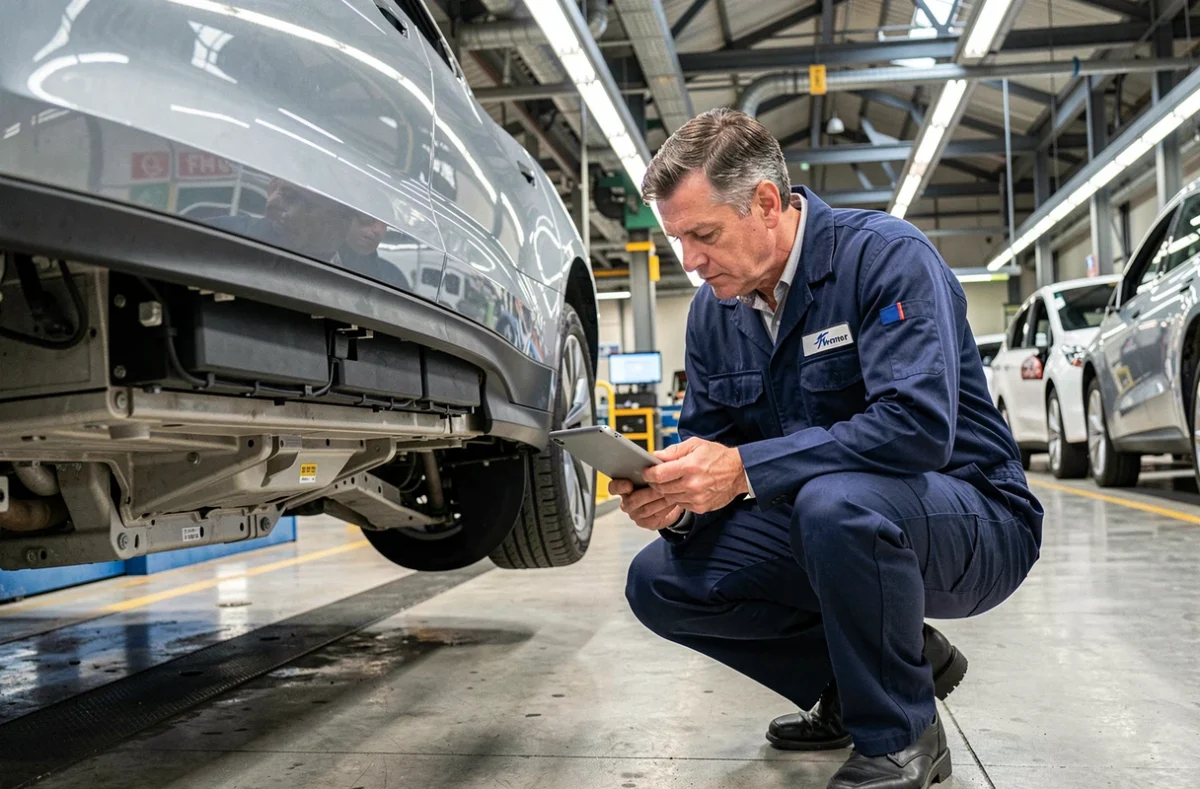
Registration figures measure consumer demand. They do not measure whether the UK can actually build the vehicles it needs to sell. A 2026 report covered by Yahoo Finance, produced by New AutoMotive, flags a structural gap: confirmed UK battery-cell capacity falls short of projected needs, and domestic production of cathode and anode materials remains incomplete.
This matters because of a looming trade deadline. Under UK-EU trade arrangements, stricter rules of origin for batteries take effect from 1 January 2027. After a one-off extension, vehicles exported to the EU must contain a higher proportion of domestically or partner-sourced battery content to avoid tariffs.
The EU remains a major export market for UK-built cars. If manufacturers cannot source enough battery components locally or from approved partners, they face tariffs that erode the competitiveness of UK-assembled EVs. The announced capacity from gigafactory projects does not automatically translate into a functioning supply chain, and the New AutoMotive figures should be read as forecasts rather than confirmed operating output.
ZEV mandate review and what it changes for 2026
The Department for Transport opened a formal consultation in August 2026 on the future trajectory of the ZEV mandate. The review considers adjustments from 2027 onwards, including options to lower the 2030 car target or extend compliance flexibilities for manufacturers.
A point that often gets lost in headlines: the 2026 ZEV target itself is not affected by this review. Manufacturers still face their current obligations for the year. The 2030 phase-out date for new pure petrol and diesel cars also remains outside the scope of this consultation.
What the review signals is regulatory uncertainty beyond 2026. Manufacturers planning model line-ups and factory investments need stable targets to commit capital. A review that might soften future requirements could, paradoxically, slow short-term investment if companies adopt a wait-and-see posture. The consultation is expected to conclude before any changes apply, but the timeline matters for supply-chain decisions already being made.
Consumer barriers holding back faster EV adoption in the UK
The gap between the ZEV mandate’s ambitions and actual market share traces back to a set of persistent consumer-side obstacles. According to data from the House of Commons Library, only around 3% of all cars on UK roads were fully electric by the end of 2023, even though BEVs accounted for 16% of new registrations that year. The installed base is still overwhelmingly petrol and diesel.
Three factors consistently appear in survey data and industry reporting:
- Upfront cost remains the primary barrier. A 2023 Auto Trader poll found that purchase price was the top concern for consumers considering an EV. While prices have fallen, the gap with equivalent combustion models has not closed enough for mass adoption.
- Charging infrastructure coverage is uneven across the UK. Urban areas with off-street parking fare better; renters and those in flats face a fundamentally different calculation when deciding whether an EV is practical for daily use.
- Consumer scepticism persists around range, battery longevity and residual values, particularly for buyers in the used-car market who have fewer guarantees on battery condition.
Road taxation is also evolving. Battery electric vehicles became subject to Vehicle Excise Duty (VED) and the Expensive Car Supplement from April 2025, removing a financial incentive that had supported earlier adoption. The pull-forward effect this created, with buyers rushing to register before the tax changes, partly explains the weak comparative figures in early 2025 and the subsequent rebound in 2026.
UK battery production: the Cornwall lithium project and remaining gaps
On the supply side, the government has pointed to the new lithium mine in Cornwall as a step toward securing domestic raw materials for battery production. The project aims to extract lithium from geothermal brines, supporting UK industrial capacity and skilled jobs in the region.
A single mine does not resolve the broader supply-chain challenge. The New AutoMotive report’s assessment highlights that gaps remain across multiple stages of battery production, from raw-material processing to cell assembly. The UK’s ability to meet rules-of-origin thresholds and maintain competitive EV manufacturing depends on whether these projects reach commercial scale within the required timeframe.
The transition is measurable and real: two million BEVs registered, a market share above a quarter of new sales, and regulatory architecture that has not retreated from its core targets. The constraint is not demand alone, but whether UK battery supply capacity can match the pace set by registration figures before trade deadlines and mandate targets tighten further.